Why 600,000 Square Meters of New Offices Are Changing the Rules
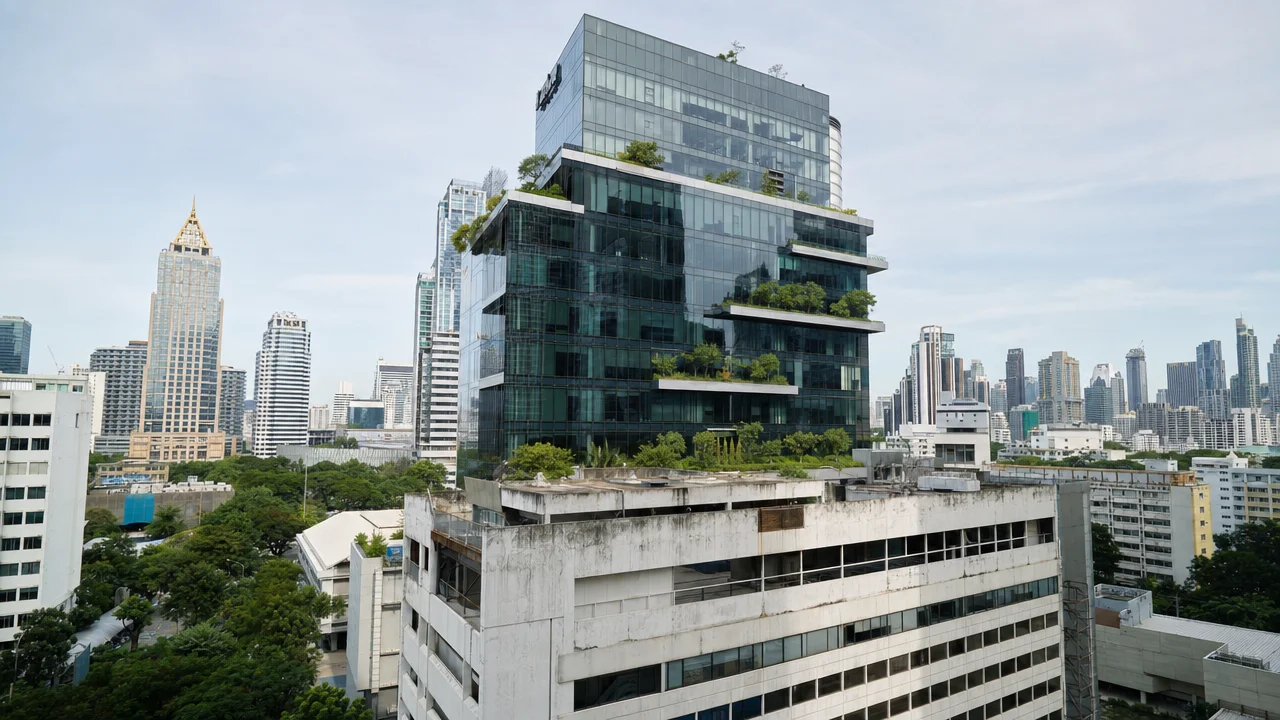
Between 2026 and 2031, more than 616,000 square meters of new office space will enter Bangkok's market. Owners of old business centers face a choice: invest millions in reconstruction or watch tenants move to modern complexes with energy-efficient systems and green certifications. The average rental rate for Class A offices holds at 943 baht per square meter per month, but behind this stability lies fierce competition. Buildings over ten years old-accounting for about 58% of the capital's total office stock-are losing tenants faster than they can modernize. This situation directly affects residential property owners in Pattaya: the mechanics of obsolescence work the same for offices and condominiums.
What's Happening in Bangkok's Office Market
Total office space in the capital in Q2 2026 reached approximately 9.15 million square meters. The structure breaks down as follows: 38% Class A properties, 58% Class B buildings, and the remaining 4% Class C. More than half of Class B buildings and older Class A properties have been in operation for over ten years.
Tenants are massively relocating from outdated buildings to new complexes. The reason isn't just prestige. Modern business centers offer intelligent building management, energy-efficient engineering systems, environmental certifications, and developed infrastructure with recreation areas and sports facilities. Even at comparable rental costs, international companies choose to relocate.
Old property owners are forced to respond. They modernize engineering systems, update public spaces, renovate premises, and improve services. Investments reach tens of millions of baht per property. The alternative-rising vacancy rates and falling profitability.
Geography of New Supply: Where the Market Is Shifting
New projects increasingly appear outside the central business district. Developers are exploring eastern Sukhumvit, Bang Na-Trat Road, and Phahon Yothin. These areas attract companies with lower rental rates and modern infrastructure. For central locations, this means additional pressure: competition exists not only between old and new buildings, but also between districts.
Until 2031, approximately 616,000 square meters of new offices are planned. This equals roughly 6.7% of current supply. The figure seems manageable, but the problem lies in concentration: most new supply consists of Class A properties with high standards. They directly compete with existing premium buildings while simultaneously drawing tenants from Class B.
How Old Buildings Try to Survive
Modernization requires a comprehensive approach. Replacing elevators, air conditioning systems, and lighting is the basic minimum. Tenants expect smart climate control systems, energy-saving technologies, and quality ventilation. Obtaining environmental certifications becomes a competitive advantage.
Public spaces play an increasingly important role. Lobbies, relaxation zones, cafes, meeting rooms-these are no longer options but standards. Companies seek offices that help attract and retain employees. Buildings without quality infrastructure lose even with lower rental rates.
Old property owners offer tenant bonuses: discounts on initial months, improved fit-out conditions, flexible contract terms. The market is shifting from price competition to quality competition. Those unwilling to invest in reconstruction risk being left with empty spaces.
Parallels with Residential Real Estate: Pattaya Condominiums Under Pressure
The mechanics working in Bangkok's office market apply to Pattaya's residential real estate. In Bangkok alone, there are about 220,000 unsold condominiums; nationwide-approximately 400,000 units. Thai Real Estate Information Center President Dr. Sopon Pornchokchai calls the situation the worst in thirty years, since the 1997 Asian financial crisis.
Unrealized inventory nationwide exceeds 600,000 properties. Part of this volume falls on Pattaya. The number of new construction permits in Q1 2026 dropped 44.3% in the metropolitan region, with the condominium segment down 71.3%. Only 2,950 apartments received approval.
The paradox: excess old projects pressure the market, but fewer new offerings appear. In Pattaya, quality beachfront projects with reliable developers maintain value. Second and third-line properties, especially in older buildings, lose competitiveness.
What Becomes Obsolete Faster: Engineering or Location
Average square meter costs in Central Pattaya hold in the 80,000-120,000 baht range for beachfront projects and 50,000-70,000 baht for second-line properties. Na Jomtien is cheaper: 60,000-90,000 baht per square meter in new complexes and 40,000-60,000 baht in the secondary market.
No direct price collapse is occurring. Developers prefer to maintain prices and reduce construction volumes rather than engage in price dumping. A sharp drop in value would destroy company balance sheets and trigger a wave of bankruptcies. Builders make concessions: 5-10% discounts, installment plans, bonuses in the form of furniture or initial service years.
The secondary market has already undergone correction. Properties purchased in 2015-2017 at inflated prices sell at 15-20% discounts from original cost. This creates competition for new developments but simultaneously forms a price floor.
Short-Term Rental Versus Long-Term: Changing Models
The average rate for a 30-square-meter studio in Central Pattaya during high season fell from 1,500-2,000 baht per night in 2019 to 1,200-1,500 baht in 2026. The short-term model only works in central districts and beachfront areas. Competition among old stock has grown so much that owners reduce rates or switch to long-term rentals.
Long-term rental becomes more predictable. Expats, remote workers, and winter visitors are willing to rent housing for 6-12 months at rates of 15,000-25,000 baht per month for a one-bedroom apartment. Yield is lower-about 4-5% annually-but stability is higher.
Na Jomtien attracts buyers focused on peaceful seaside living. Demand for long-term rentals here is more stable than in the center. Projects with good infrastructure-pools, fitness centers, security-maintain prices.
Which Pattaya Districts Are Under Greatest Pressure
Central Pattaya, especially the Walking Street and Beach Road zone, maintains demand due to tourist traffic. Studios and one-bedroom apartments here remain liquid, although short-term rental yields have decreased.
Areas under greatest pressure are second and third-line districts: Pratumnak with old unrenovated buildings, second-row Jomtien, and Naklua far from the beach. These areas concentrate properties built during the 2015-2018 boom. Many are poorly maintained, management companies work poorly, and infrastructure is worn.
Buyers with budgets of 2.5-3 million baht choose Pattaya because in Phuket these funds only buy a studio far from the beach. Pattaya offers more beachfront options. Focus on long-term rental with proper property selection yields 4-5% annually. The key condition-a quality project with good management.
Role of Management Company: Why It's Critical
The management company determines whether a building will maintain value or become a semi-abandoned property with leaking pools. In Bangkok's office market, tenants leave not only due to outdated engineering but also poor service quality.
In residential real estate, the situation is similar. A building with a good management company maintains attractiveness even ten years after completion. Poor management kills a project in two to three years. Signs of a quality management company: timely common area repairs, clean grounds, functioning security systems, transparent financial reporting, quick response to resident requests.
Before purchasing an apartment, check the management company's reputation. Talk to current residents, study reviews, assess common area conditions. Low service costs aren't always an advantage. Often this means economizing on critical things: security, cleaning, repairs.
Foreign Buyers: Volumes and Forecasts
Forecasts indicate foreigners will complete about 15,200 transactions throughout Thailand in 2026. This is only 5% of the market. Growth compared to 2025 will be just 1.8%. Pattaya traditionally attracts Russian-speaking buyers, Chinese, Europeans, but volumes are far from pre-crisis levels.
The entry threshold in Pattaya is lower than Phuket, where a beachfront studio costs from 4-5 million baht. In Pattaya, options start from 2-2.5 million baht in new Na Jomtien projects. Demand from budget-limited buyers persists.
Foreign investors remain active but their share is small. They seek projects with strong management, good location, and adequate pricing. Buying an apartment in a project that becomes problematic in two years-a direct path to losses.
Development Scenarios: Stagnation Instead of Collapse
Collapse-a sharp 20-30% price decline over a short period. Such a scenario isn't visible in Pattaya yet. Developers prefer to maintain prices and reduce construction volumes. A sharp value drop would destroy company balances.
Prolonged stagnation is more likely. Prices will remain at current levels or decrease 5-10% in nominal terms. Real rental returns will continue falling due to competition. Liquidity will worsen: selling an apartment quickly at the desired price will become harder.
Pattaya remains one of Thailand's most affordable coastal locations. Demand from budget-limited buyers persists. The market transitions from growth phase to selection phase. Winners are projects with strong management, good location, and adequate pricing. Losers are old buildings, second-line properties, everything built hastily during the boom.
What This Means for Pattaya Buyers
Bangkok's office crisis demonstrates a universal pattern: new high-quality supply displaces old properties if they don't modernize. The same mechanics work in Pattaya's residential real estate. Buyers need to understand three things.
First: no need to rush. Prices aren't rising, supply is broad, you can choose. The market is in correction phase, developers are willing to make concessions. Discounts of 5-10%, installments, bonuses-standard practice. Pressure on sellers will continue at least until 2027-2028.
Second: checking the developer and management company is critically important. Buying an apartment in a project that becomes a semi-abandoned building in two years-a direct path to losses. Study the developer's reputation, financial stability, portfolio of completed projects. Talk to residents of this developer's existing properties.
Third: betting on long-term rental and personal use is safer than counting on a tourist boom. Short-term rental only works in central districts and beachfront areas. Competition among old stock is high. Long-term rental yields 4-5% annually with proper property selection. This is lower than marketers promise but realistic.
Priority-quality projects with good management, beachfront or first-line location, reliable developer. Second and third-line properties in old buildings lose competitiveness faster. Savings on purchase can turn into rental and resale problems.
Conclusions: From Boom to Selection
Bangkok and Pattaya's real estate market transitions from growth phase to selection phase. The capital's office centers face pressure from new supply exceeding 616,000 square meters. Old buildings lose tenants if they don't invest in modernization. Average Class A office rental rates hold at 943 baht per square meter, but fierce competition hides behind this stability.
Pattaya residential real estate experiences similar pressure. About 220,000 unsold condominiums in Bangkok and over 400,000 nationwide create excess supply. Fewer new projects are launching, but quality beachfront properties maintain value. Old second and third-line buildings lose.
Buyers need to understand: the market won't collapse, but stagnation will last several years. Prices will remain at current levels or decrease 5-10%. Rental yields will fall due to competition. Liquidity will worsen. Betting on quality, checking developers and management companies, focusing on long-term rental-three principles that help avoid losses and preserve investment value.